



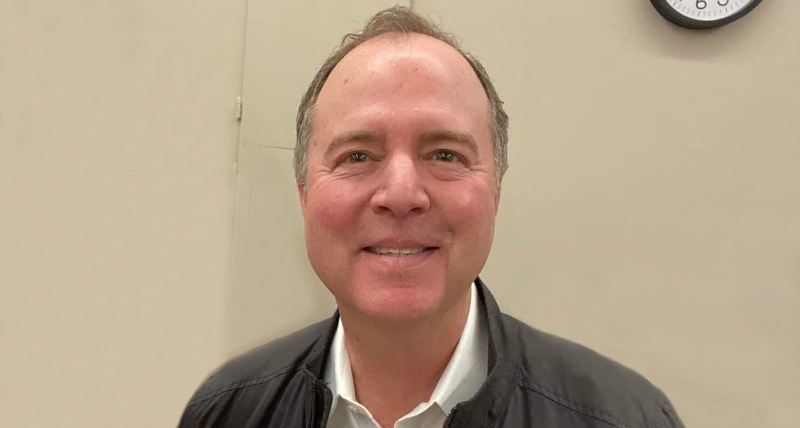
Representative Adam Schiff via Facebook
In a letter to the Federal Insurance Office (FIO) and the National Association of Insurance Commissioners (NAIC), Representatives Adam Schiff (D-Pasadena) and Mike Levin alongside Senator Elizabeth Warren called for comprehensive and transparent data collection to understand and address the impact of climate change on property insurance premiums.
The letter urges FIO to use its subpoena power to compel states to participate in FIO’s data collection call and pushes the NAIC and FIO to publish the deidentified raw data for researchers and the public. The letter is signed by 21 Members of Congress.
Last week, Alameda County District Attorney Pamela Price accused the insurance companies of “operating a widespread scheme” on California consumers, leaving them underinsured in a disaster like a wildfire.
Alameda County’s Consumer Justice Bureau filed the lawsuit against some major insurance carriers representing 15% of the homeowners’ policies in the state of California. All are affiliates of Farmers Insurance and include Mid-Century and others who District Attorney Price says are engaging in unlawful business practices.
“We are deeply concerned about the impact of rising homeowners’ insurance premiums on our constituents,” according to the letter. “We have seen families reduce their coverage to cope with rising costs, making them even more vulnerable to a potential natural disaster. In some states, major insurers are pulling out entirely, leaving households scrambling for coverage or simply going without.”
The County has also taken steps to address the rising costs faced by local homeowners.
In March, after receiving a report that some home insurance premiums in Pasadena have risen by a staggering 600%, County Supervisors Kathryn Barger and Lindsey P. Horvath filed a motion on aiming to address the challenges that homeowners face in securing fire insurance.
Barger and Horvath said stabilizing the fire insurance market is crucial due to various challenges that the state is facing — including a housing shortage, climate impacts like increased fire danger, and limited insurance options.
The supervisors also said recent legislation aimed at addressing these issues has revealed disparities between intentions and outcomes; they cited Assembly Bill 3074 which mandates the removal of flammable materials near structures to mitigate fire risk.
“Despite the passage of this law by the state legislature, the California Board of Forestry and Fire Protection has not yet defined AB 3074’s implementation requirements and it is unclear when a final determination will be made,” Barger and Horvath said in the motion. “To further complicate matters, the escalating severity of wildfires plaguing the State of California has also prompted insurance providers to adopt more conservative approaches: limiting or outright ceasing the issuance of new home insurance policies and applying additional fire mitigation requirements as a condition of being insured.”
Because of the situation, the supervisors said many homeowners have been forced to rely on expensive options, such as the California Fair Access to Insurance Requirements (FAIR) Plan.
“The FAIR Plan is one of the most expensive options available to residents of California and Los Angeles County,” the motion said. “This is especially challenging financially for disadvantaged communities, as well as seniors and others on fixed incomes. While the establishment of mitigation and buffer zones directly adjacent to a structure are deemed essential to safety, these additional mandates are leading to a situation of rapidly escalating financial burdens for homeowners who are already grappling with increased costs of inflation.”
To address these concerns, Barger and Horvath said authorities must support legislation stabilizing the fire insurance market, consider local input in implementing AB 3074, and investigate compliance measures imposed by insurance companies.
The motion directs the County’s interim Chief Executive Officer to consult with the Los Angeles County Fire Chief and communicate with the California Board of Forestry and Fire Protection and the State Insurance Commissioner to call for action on these issues.
“Homeowners are facing uncertainty and are increasingly being forced to try to navigate an insurance market in crisis,” the motion said. “It is paramount that the County work directly with the State to protect homeowners facing a daunting financial challenge, while trying to ensure they have basic insurance coverage in the face of changing climate patterns that have rapidly increased the risks of wildfires they face.”
In March, State Insurance Commissioner Ricardo Lara announced efforts to fix the home insurance market. Lara introduced two regulations. The first aimed to streamline rate reviews.
The second regulation allows insurers to use catastrophe modeling, the modeling combines historical data with projected risk and losses. Other factors are also considered when premiums are established.
According to state law, the Insurance Department can approve or deny insurance companies requests to raise premiums.
Those companies say the process has been holding up necessary increases to make up for increased costs brought on by rising climate-change risks and inflation.
“Congress created the Federal Insurance Office (FIO) to monitor issues and gaps in insurance regulations that could contribute to a systemic crisis and leave traditionally underserved communities without access to affordable insurance products,” the letter adds. “Therefore, we urge FIO to use its subpoena power to compel any states who fail to participate voluntarily to submit their data, and the National Association of Insurance Commissioners (NAIC) to publish the names of any states that refuse to participate. We also urge you to publish all deidentified reported data for public use.”
 Get our daily Pasadena newspaper in your email box. Free.
Get all the latest Pasadena news, more than 10 fresh stories daily, 7 days a week at 7 a.m.